Local claim snapshot
- County
- Anoka County
- Region
- Twin Cities Metro
- Housing
- 1960s–1970s ramblers to 2000s two-stories
- Storm history
- May 6, 1965 Fridley tornadoes
Common perils
- Hail
- Tornadoes
- Straight-line wind
- Ice dams
- Frozen pipes
Neighborhoods we inspect
- The Lakes
- Club West
- Laddie Lake
- Lexington Avenue corridor
- Paul Parkway area
- Northtown area
Tornado country in the north metro
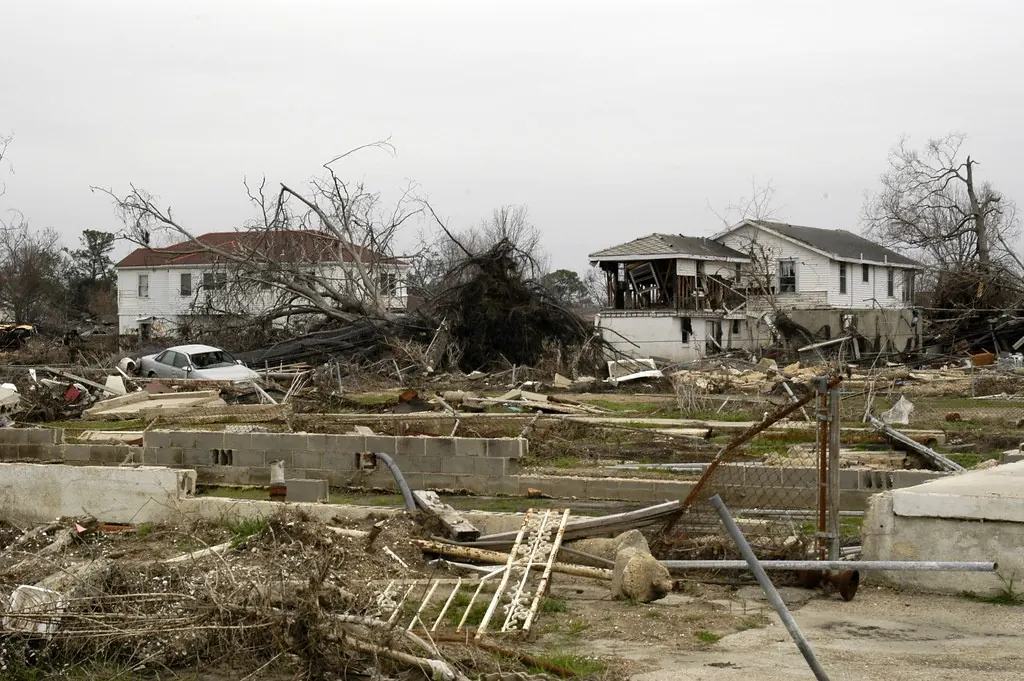
On May 6, 1965, a series of tornadoes struck the northern Twin Cities, with Fridley and neighboring Anoka County communities among the hardest hit. Hundreds of homes were damaged or destroyed. More than half a century later, Anoka County still sees regular severe weather: hail, straight-line winds and the occasional tornado. In May 2008, a tornado tore through Hugo, just east of the county line, a reminder that the risk hasn’t gone away.
Blaine’s housing mix
Blaine’s older neighborhoods in the south part of the city, near Northtown and along University and Central Avenues, were built mainly in the 1960s and 1970s and consist largely of ramblers, split-entries and small two-stories. North of 109th Avenue, developments such as The Lakes and Club West added larger homes from the 1990s through the 2010s, often with association covenants. Townhome communities are spread throughout.
Older homes
Older Blaine houses often have multiple roof layers, aluminum or steel siding no longer made, and original windows. Matching is often the main dispute.
Newer homes
Newer homes bring steep, complex roofs and premium siding and stone accents, all of which push repair costs above a basic estimate.
Where we focus on Blaine claims
- Wind claims where uplift and creasing are dismissed as wear.
- Hail claims limited to soft metals without a full roof inspection.
- Siding that can’t be matched, leaving mismatched elevations.
- Tree-strike claims where removal and structural repairs are lumped together.
What appraisal can and can’t do
Appraisal is a focused tool. It decides the amount of loss: the scope of covered damage and what it costs to repair. It doesn’t decide whether your policy covers a peril, whether an exclusion applies or whether the insurer acted in bad faith. Those questions go to the insurer, the Minnesota Department of Commerce or the courts.
Within its lane, appraisal can be faster and less expensive than litigation. Each side pays its own appraiser, and the umpire’s fee is usually split. An agreement signed by any two of the three, either both appraisers or one appraiser and the umpire, typically sets the amount. For Blaine homeowners with a wind or hail claim where the insurer agrees there’s damage but offers too little, that structure often works well. For claims where coverage itself is denied, talk to an attorney first. We’re glad to tell you which category your claim seems to fall into after reviewing the file.
Help for Anoka County owners
Minnesota Insurance Appraiser comes to the property, builds an independent estimate and represents you if you invoke appraisal. We serve Blaine, Coon Rapids, Ham Lake, Lino Lakes, Andover and the rest of Anoka County. See tornado and wind appraisal or hail and roof appraisal, or reach out with your estimate.
Appraisal solutions available in Blaine
Every Minnesota Insurance Appraiser solution is available to property owners in Blaine and the surrounding communities, including:
- Appraisal Clause Representation
- Homeowner Claim Appraisal
- Commercial, Townhome & HOA Claims
- Roof & Hail Damage Appraisal
- Tornado, Derecho & Straight-Line Wind
- Water & Burst-Pipe Claims
Questions from Blaine property owners
What’s the difference between tornado and straight-line wind for insurance purposes?
For most homeowner policies, both fall under windstorm coverage. The difference matters more for how damage is documented than whether it is covered.
Can I invoke appraisal if my insurer hasn’t finished the claim yet?
Appraisal is usually available once there is a disagreement over the amount. Many policies also set deadlines for lawsuits, so don’t wait too long. Read your policy or ask a lawyer about timing.