Why winter claims are different here
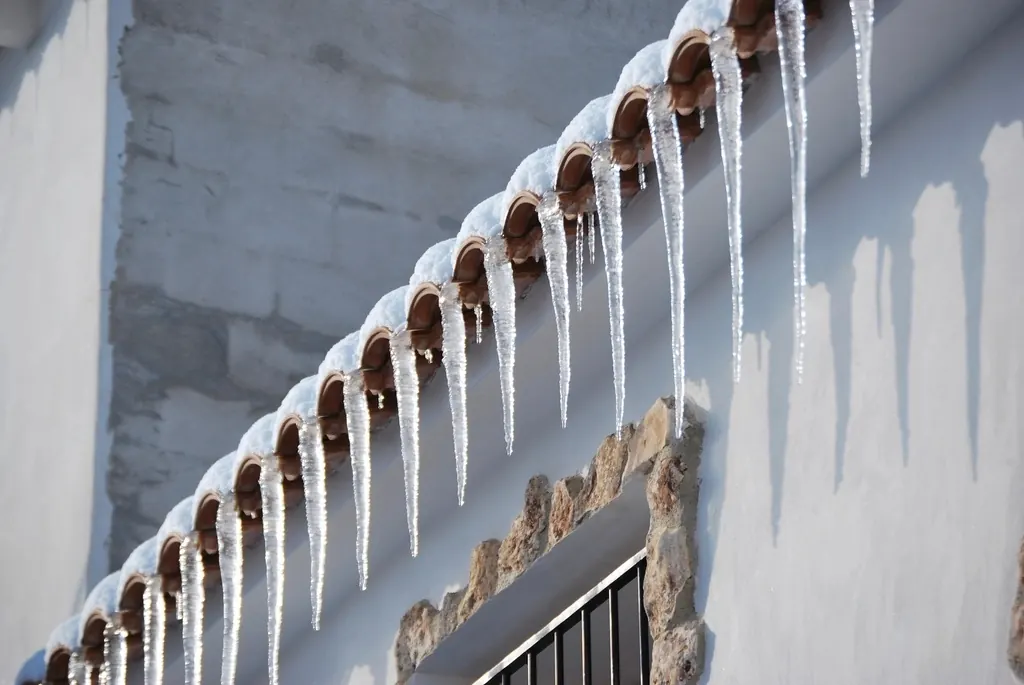
Long stretches below freezing, heavy snow, and rapid thaws make Minnesota a textbook setting for ice dams. Heat escaping through the attic melts snow on the upper roof, the water runs down to the cold eaves, refreezes, and builds a ridge of ice. Meltwater then backs up under shingles and into the house. Winters such as 2010–11 and 2022–23 produced waves of these losses across the Twin Cities and beyond. An ice dam insurance claim can involve ceilings, walls, insulation, windows and flooring, often well away from the eaves where the problem started.
The three winter loss types we handle
Ice dam water intrusion
Many homeowner policies cover interior damage caused by ice dams, but some limit coverage for the roof itself or exclude damage from long-term seepage. The insurer may accept the interior loss while undervaluing it, for example by drying and painting a ceiling without replacing wet insulation or addressing stained plaster.
Snow load and collapse
The most famous example of snow load failure in Minnesota is the Metrodome, whose fabric roof deflated under heavy snow in December 2010. Homes, garages, pole barns and commercial roofs can also sag or fail when snow and ice accumulate. Collapse coverage is often defined narrowly, and policies differ on whether partial sagging counts. Once coverage is accepted, appraisal can determine the cost of structural repair.
Frozen and burst pipes
Seasonal cabins in lake country and along the North Shore are particularly vulnerable. A furnace fails or the power goes out, and pipes freeze and split. When the thaw comes, water runs for days before anyone notices. Policies frequently require that heat be maintained or the water system be drained when a home is vacant or unoccupied, which can raise coverage questions. Where the loss is accepted, the scope should include the full extent of the water spread, not just the visible damage.
What we look for in a winter claim
- Moisture in insulation, top plates and wall cavities below the ice dam line
- Staining and delamination in plaster ceilings common in older homes
- Damage to windows and trim where meltwater entered
- Roof decking and underlayment condition at the eaves
- Structural deflection in rafters or trusses after heavy snow
- Mold growth from slow drying in cold-season conditions
Our approach
Minnesota Insurance Appraiser inspects the interior with moisture meters and, where safe and the season allows, the roof edges and attic. We build an independent scope that follows the water from the eaves to every affected surface. For an ice dam insurance claim, we also note when attic insulation and ventilation were damaged by the event itself, which the insurer’s estimate may skip.
Mold and delayed discovery
Ice dam leaks often run quietly inside a wall for weeks before a stain appears. By then, insulation may be saturated and mold may be growing on framing or the back of drywall. Many policies limit mold coverage or cap it at a fixed amount, which is a coverage matter, but the cost of removing wet materials as part of the water repair is usually part of the main scope. Careful documentation of when the leak was first noticed and what was done helps keep the claim focused on the covered event.
When to reach out
Winter losses are often reported weeks after they begin, so document dates and conditions carefully. Review your policy for deadlines, then contact us. Water losses unrelated to winter are covered on our water damage page, and general terms are explained on the insurance terms page.
Frequently asked questions
Does homeowners insurance cover ice dam damage?
Many Minnesota policies cover interior water damage caused by ice dams, though some limit coverage for the roof or exclude gradual seepage. Your specific policy controls.
My cabin pipes froze while I was away. Can I still use appraisal?
If the insurer accepts the claim but disputes the amount, appraisal is available. If it denies the claim based on a vacancy or heat-maintenance condition, that is a coverage issue for an attorney.
Will the insurer pay for ice dam removal?
Removal to prevent further damage is often treated as a reasonable mitigation cost. Keep the invoice and photographs.