Hail in Minnesota
Severe hail is a recurring part of Minnesota summers. Storms that build across the southern half of the state, from Mankato and Rochester up through the Twin Cities, can drop stones large enough to bruise shingles, dent metal and crack vinyl in a few minutes. Because so much of the state’s housing uses steel or aluminum siding, hail claims here often turn on exterior metal as much as on the roof itself.
What a full hail scope should cover
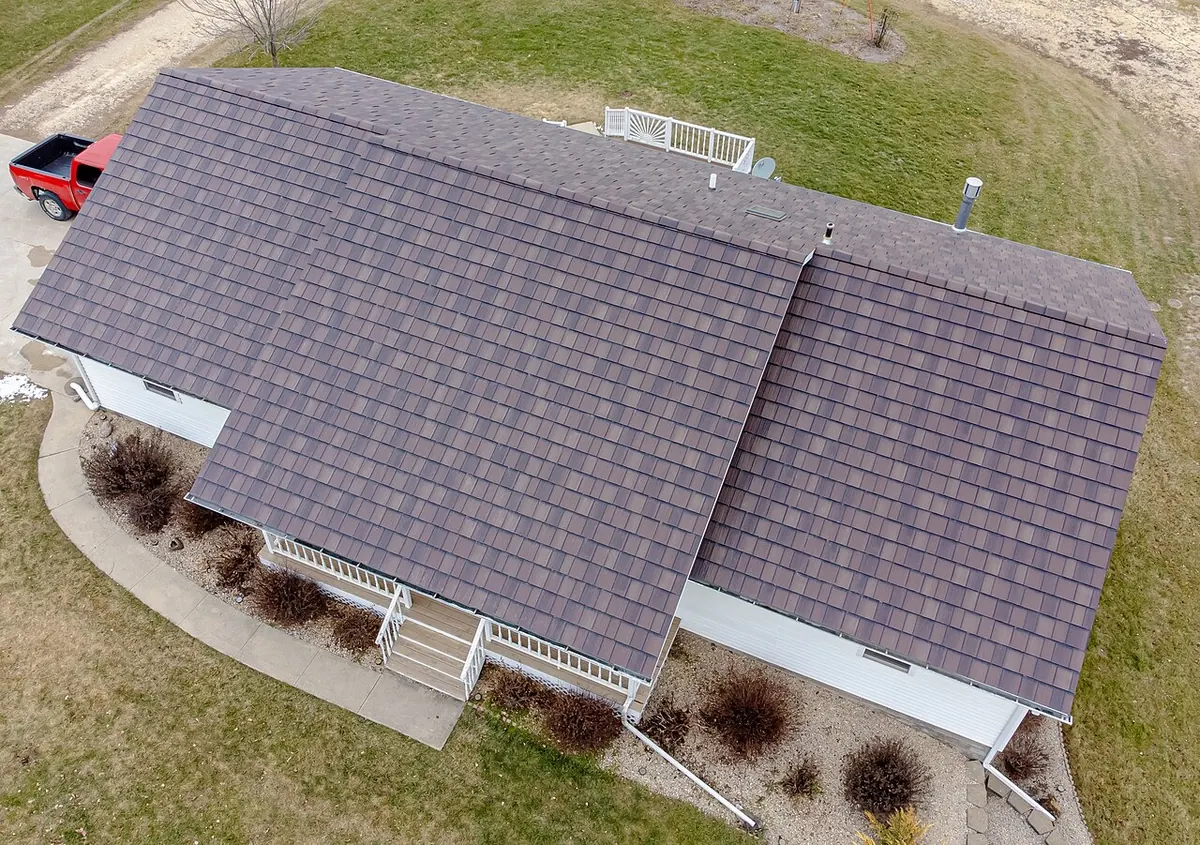
- Roof covering. Asphalt shingles, cedar shakes, metal panels and low-slope membranes each show hail differently. Test squares, granule loss and mat fractures should be documented, not assumed.
- Steel and aluminum siding. Dents in metal siding are permanent. Whether they are functional or cosmetic, and whether the policy has a cosmetic damage exclusion, matters a great deal.
- Gutters, downspouts and soft metals. Roof vents, flashings, chimney caps and AC fins often show the clearest evidence of the storm’s size.
- Window wraps and screens. Aluminum capping around window and door frames is easy to miss and expensive to replace.
- Matching. Discontinued siding profiles and colors are common on older ramblers. If a repair cannot reasonably match, the dispute over how far replacement should extend is central.
Cause and amount
Insurers sometimes accept a hail claim but attribute part of the damage to wear, prior storms or installation defects. Because the Minnesota Supreme Court in Quade v. Secura Insurance (2012) recognized that appraisers may determine causation as part of determining the amount of loss, these disagreements can often be addressed on the appraisal panel. Whether a particular item is covered at all is still a matter for the policy and, if necessary, the courts.
| Component | What we document |
|---|---|
| Shingles | Hits per test square, bruising, mat damage, age |
| Steel siding | Dent density by elevation, profile and color availability |
| Soft metals | Spatter and dent size as storm evidence |
| Window wraps | Dents, creases, separation from frame |
Common reasons hail claims are underpaid
Underpaid hail files tend to share the same handful of issues. The roof is approved for repair rather than replacement even though the shingle line is discontinued. Only the elevation facing the storm is approved for siding. Gutters are listed but downspouts, window wraps and fascia metal are not. Ice and water shield, drip edge and starter course are left off even though local practice and code call for them. Each of these can be priced and argued within a Minnesota hail damage appraisal, and together they often explain most of the difference between an insurer’s figure and a contractor’s bid.
Timing and documentation
Hail damage is easiest to prove soon after the storm, when spatter marks on painted surfaces are fresh and before the next storm complicates the picture. Take dated photos, keep any National Weather Service storm reports you find, and note the date carefully. Minnesota policies commonly limit lawsuits to two years after the loss, so confirm that deadline in your policy and with an attorney.
Working with Minnesota Insurance Appraiser
We start with the insurer’s roof report and estimate, then perform our own inspection, including the roof where it is safe to access. Our Minnesota hail damage appraisal scope prices replacement at local material and labor rates and flags matching and code items clearly. You can learn more about the panel steps in our appraisal process guide, and wind-related roof losses are covered on the tornado and wind page. Ready to talk? Contact us.
Frequently asked questions
My insurer says the siding dents are cosmetic. Can appraisal help?
Appraisal can value the damage, but whether a cosmetic damage exclusion applies is a coverage question. If your policy has such an endorsement, an attorney may need to weigh in on that part.
Does a full roof replacement depend on how many hits per square?
There is no single statewide rule. Insurers use internal guidelines, and the appraisal panel considers the actual condition, repairability and matching of the roof.
What if the storm happened over a year ago?
Appraisal may still be possible, but older claims raise documentation and deadline concerns. Check your policy’s suit limitation and talk with an attorney promptly.