Why homeowner claims stall
Most homeowners do not dispute that their claim was accepted. They dispute the check. A typical complaint is that the adjuster’s estimate looked thorough but the contractor’s bid came in at nearly double. When that happens the gap almost always traces to specific line items that can be identified and argued, which is exactly what a Minnesota home insurance appraisal is built to do.
Minnesota houses are not generic
Estimating software applies default assumptions. Minnesota’s housing stock regularly breaks them.
Early-century city homes
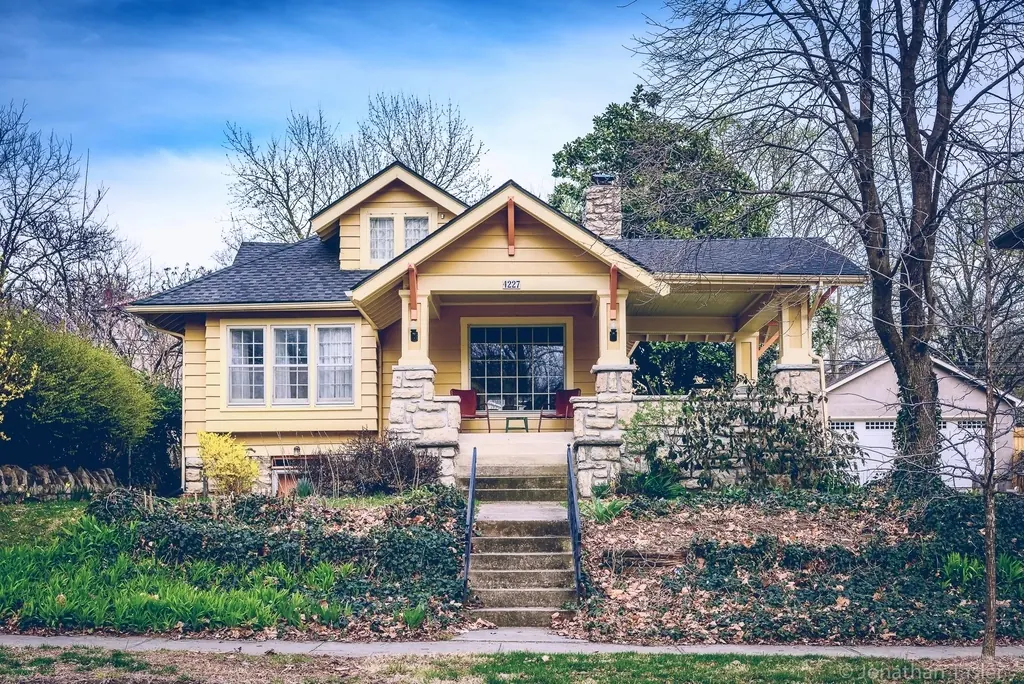
Four-squares and bungalows built in Minneapolis and St. Paul in the 1910s and 1920s often have three-coat plaster on wood lath, old-growth trim, and built-ins that cannot be matched with stock millwork. An estimate that swaps plaster for half-inch drywall and paint is not a like-kind repair.
Postwar ramblers and split-levels
First-ring suburbs such as Richfield, Roseville, Fridley and Bloomington are full of 1950s to 1970s homes with steel or aluminum siding, original hardwood under carpet, and mechanical systems that need code upgrades once walls are opened.
Lake cabins and seasonal homes
Cabins in the Brainerd lakes area or along the North Shore add access issues, longer contractor travel, limited local labor in peak season, and losses that sat unnoticed for weeks. Each of those affects cost and should appear in the estimate.
Common items we see left out
- Matching for siding, flooring or cabinets where the undamaged portion cannot reasonably be blended with new material
- Code-required upgrades, if your policy includes ordinance or law coverage
- Contractor overhead and profit on jobs that need more than one trade
- Contents manipulation, protection of finished floors, and debris removal
- Winter conditions such as heat for drywall finishing or temporary enclosures
| Line item (illustrative) | Insurer estimate | Appraiser’s scope |
|---|---|---|
| Plaster wall repair, living room | $1,400 (drywall) | $4,100 (plaster) |
| Siding, two elevations | $2,600 (one elevation) | $6,900 (matching) |
| Overhead and profit | Not included | Included |
The figures above are illustrative only and do not describe any actual client or claim.
Replacement cost, actual cash value and holdback
Most Minnesota homeowner policies pay replacement cost in two steps. The first check reflects actual cash value, meaning the repair cost minus depreciation. The withheld depreciation is released once repairs are completed, usually within a time limit stated in the policy. When an estimate is too low, both checks shrink. Appraisal sets the replacement cost figure and, where the award form calls for it, the actual cash value figure as well, so the eventual recovery is measured from the right starting point. Ask about these numbers early so a holdback deadline does not pass unnoticed.
What working with us looks like
Minnesota Insurance Appraiser starts by reading your policy and the carrier’s estimate side by side. If appraisal looks appropriate, we inspect the home, build our own line-item scope, and then meet the insurer’s appraiser to narrow the differences. Anything still unresolved goes to the umpire. Throughout, we keep you informed about what is being argued and why.
Before you call
Gather your declarations page, full policy, the adjuster’s estimate, any denial or partial-payment letters, photos from the day of the loss, and contractor bids. A Minnesota home insurance appraisal moves faster when those are ready. Our free tools include checklists, and the insurance terms page explains words like depreciation and holdback. When you are ready, reach out.
Frequently asked questions
Does appraisal work for a cabin that isn’t my primary home?
Yes, if the cabin policy contains an appraisal provision, which most Minnesota property policies do. Seasonal-use conditions in the policy may still affect coverage, which appraisal does not decide.
Will my insurer cancel my policy if I request appraisal?
Appraisal is a right written into the policy. Questions about renewal or nonrenewal can be directed to the Minnesota Department of Commerce, which handles insurance consumer complaints.
Can I keep my contractor involved?
Yes. Contractor bids and observations are useful evidence, but your appointed appraiser should be someone without a financial interest in the repair.